A restart is not a normal route
1:18 · Complete thought, with its own opening and close.
The weekly paper
for curious people
See the connections.
Understand the consequences.
Swipe to see more sections →
Issue 006 · World · Australian fuel
The war has become a problem of routes, repair and bargaining. A bypass can move oil around one chokepoint while exposing it to another.
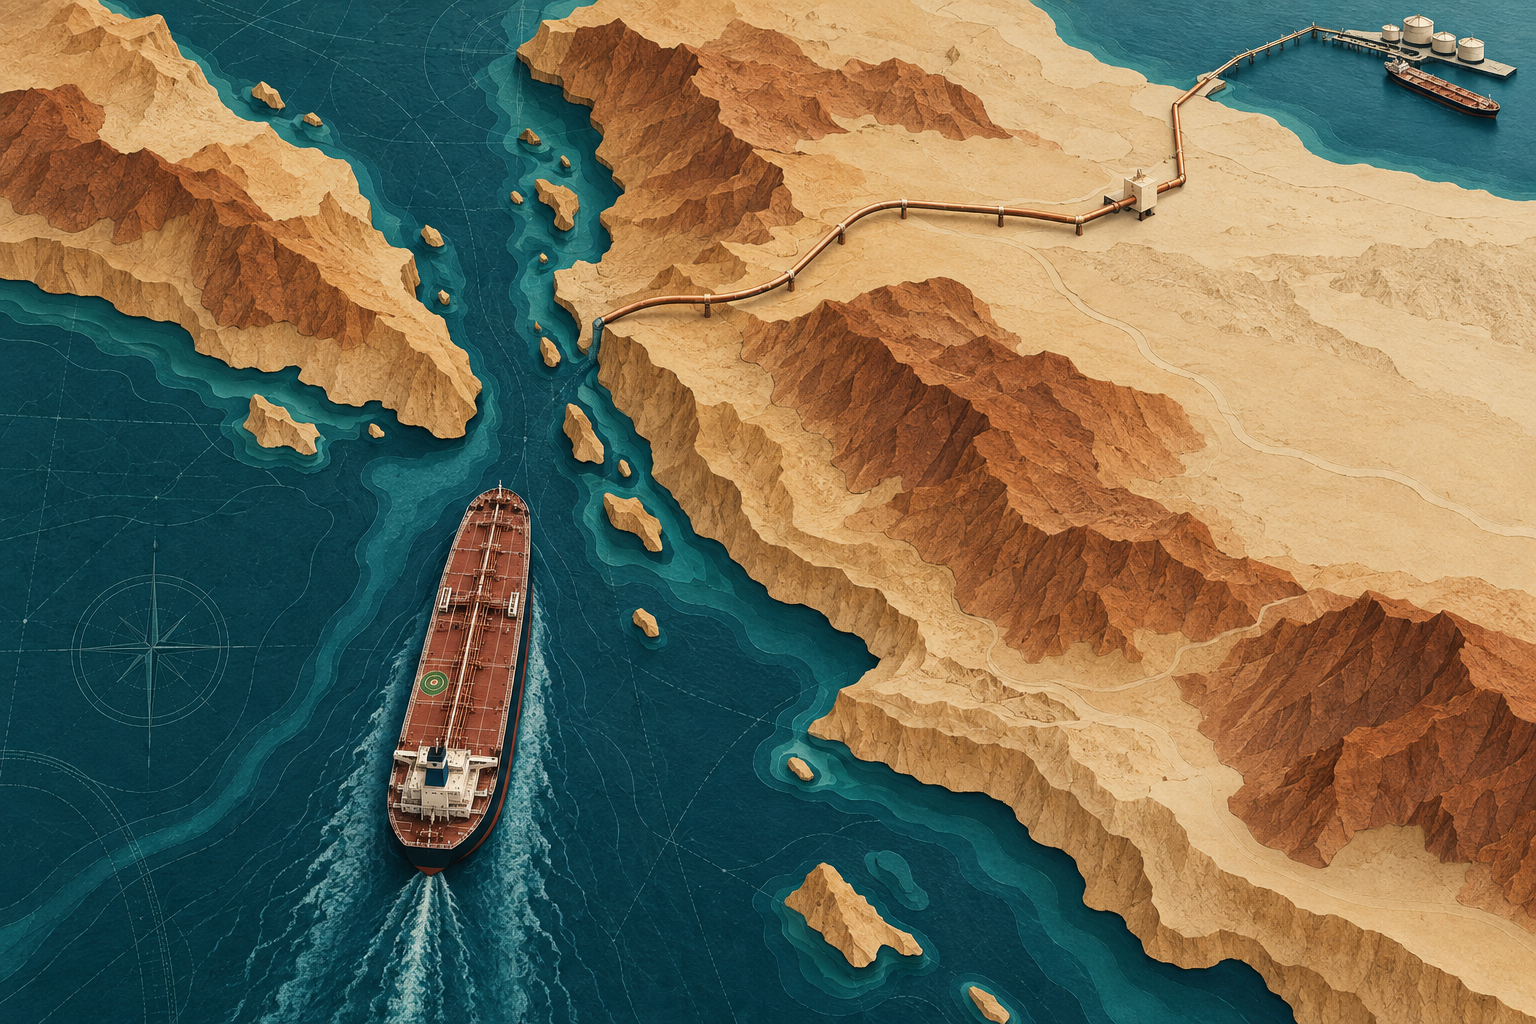
Pipeline restart reported; lasting price effect unproven
Oil needs a usable route to a refinery and fuel needs a usable route to a buyer. Reuters reported the Saudi East-West pipeline restarted on 22 September, initially at low flow. Whether that becomes reliable exports and lower Australian fuel costs remains open; refined-fuel markets, currency, tax and retail timing also matter.
Why Lens says this →Your device reads the answer and main sections on this page. This is not the two-host discussion; it uses your device's voice and may sound different across browsers. Sources and visuals remain on the page.
Lens in 8 · Updated 24 September 2026
Two Lens hosts follow the evidence from the Saudi pipeline restart to Australian fuel prices. This is a discussion, not a word-for-word reading of the article. The reporting is dated; a restart does not prove normal exports or cheaper petrol.
The same discussion with illustrated evidence cards. Captions are available in the player.
1:18 · Complete thought, with its own opening and close.
1:11 · Complete thought, with its own opening and close.
Watch through Lens · Issue 006 · 8:37
Start with fuel at 0:42, then follow the rest of the episode. The reporting and sources stay on this page.
Choose how to read this
The facts do not change. Each view uses the same published sources and leaves the same questions open.
See through another Lens
Each view notices something useful. None is allowed to stand in for the complete evidence.
Driver
My local pump price follows several links.
What this view explainsSeparate wholesale movement, taxes and retail timing.
What it may missA cheaper station does not measure the wider supply risk.
The record
Our earlier investigation followed how the war and Hormuz disruption transmitted costs abroad. On 14 September, AP cited two regional officials saying the damaged Saudi East-West pipeline might be mostly out of service for weeks. Reuters then reported a restart at low flow on 22 September. The earlier repair estimate is no longer a current description of a complete outage; sustained normal capacity and exports are not yet established by the restart report.
AP also reported expanding Houthi threats around Red Sea shipping and Saudi oil infrastructure. Oman postponed a planned regional Hormuz meeting. These are dated reports—not proof that diplomacy has ended or that a pipeline restart removes every shipping risk.
AP: Saudi pipeline damage ↗Reuters: Saudi pipeline restart ↗AP: Houthi attacks and Saudi oil routes ↗AP: Oman postpones regional meeting ↗
See how it works
⚠ Reported disruption or security risk—not a quantified capacity estimate. Northbound cargo does not pass Bab el-Mandeb.
The record
Hormuz connects the Persian Gulf to the Gulf of Oman. Saudi Arabia can move some crude west by pipeline to Yanbu on the Red Sea. That substitutes a land route for one sea passage; it still needs functioning pumps, terminals and ships.
Destination matters. Cargo leaving Yanbu for Asia may travel south through Bab el-Mandeb. Cargo heading north toward Suez does not need that southern chokepoint. A diagram that sends every Yanbu cargo through Bab el-Mandeb would create a new error while trying to explain the old one.
Crude pipelines also do not replace the LNG tanker chain. And nameplate capacity is not spare, connected, operating capacity. EIA's route analysis shows alternatives can move only part of the volume normally passing Hormuz; its historical quantities must not be passed off as today's available throughput.
Lens analysis
Reuters' shipping report describes stalled US–Iran talks alongside renewed attacks. The observable result is continuing insecurity. It does not reveal what either leadership privately regards as an acceptable deal.
Several mechanisms can sustain that gap. Destroying equipment can reduce an opponent's capacity without removing its ability to impose costs at sea. A weaker force may still make particular voyages unacceptable to an operator or insurer. Conversely, keeping that leverage may make concessions more difficult. These are explanations to test against conduct, not findings about secret motives.
Regional actors add another problem: agreement between two governments may not stop every armed group or protect every facility. Domestic political costs, regime security, alliance commitments and enforcement guarantees could affect bargaining. The inspected record does not rank those causes or establish which is decisive.
Watch for compatible public terms, actual attendance at talks, arrangements for monitoring compliance and sustained changes in attacks and transit. Those observations would strengthen an explanation of progress. Declarations of victory alone would not.
Reuters via Gulf Times: shipping slows ↗AP: Oman postpones regional meeting ↗AP: Houthi attacks and Saudi oil routes ↗
See how it works
Solid teal: petrol · Dashed rust: diesel · Axis starts at 200c/L.
| Date, 2026 | Petrol | Diesel |
|---|---|---|
| 11 Sep | 212.8 | 251.6 |
| 14 Sep | 214.7 | 252.6 |
| 15 Sep | 217.1 | 255.5 |
| 16 Sep | 221.7 | 262.7 |
| 17 Sep | 224.1 | 267.5 |
Influences along the chain—not six charges to add together. ACCC monitoring separates international, wholesale and retail prices.
The record
AIP's Brisbane average terminal gate price rose from 212.8 to 224.1 cents a litre for unleaded petrol between 11 and 17 September. Diesel rose from 251.6 to 267.5. Those are increases of 11.3 and 15.9 cents respectively, calculated from the published observations. They include GST and are indicative wholesale prices, not a survey of every forecourt.
The price chain runs through crude, refinery output, international petrol and diesel benchmarks, freight and the Australian dollar before reaching wholesale and retail pricing. Different refined products can tighten differently even when the crude price is shared.
Tax is already embedded in terminal gate prices: do not add it again. ACCC records full excise restoration on 3 August, taking excise to 53.7 cents a litre after a 17.1-cent increase. That earlier step matters to the price level; it does not explain a new tax change during 11–17 September. Retail margins, stock timing and local petrol cycles still affect the sign outside a particular station.
The record
EIA published its September outlook on 9 September using inputs finalised on 3 September. Its forecast assumes gradually improving exports, with constraints persisting into year-end. That is conditional guidance prepared before the later pipeline and Red Sea developments.
EIA's $91-a-barrel August Brent average is a monthly historical measure. It is not the price on the day you read this. Likewise, Reuters' Kpler-derived transit figures describe an earlier weekend; missing transponders and differing vessel categories limit a literal traffic count. Dating the number is part of explaining it.
EIA September Short-Term Energy Outlook ↗Reuters via Gulf Times: shipping slows ↗
Lens analysis
The 1973–74 embargo shows how deliberate supply restraint can amplify an existing inflation problem. The 1978–79 shock adds a different mechanism: physical Iranian production losses interacted with demand and fear-driven inventory buying. In both, the price response cannot be reduced to one day's lost barrels.
The 2019 Abqaiq attack illustrates vulnerability at a processing facility rather than a maritime passage. Restoring output and confidence is a different task from ending a prolonged regional conflict. Its repair experience cannot set a deadline for 2026.
These comparisons suggest useful questions. How much supply is physically unavailable? How much price reflects feared future loss? Can stocks bridge the gap? Are alternative suppliers able to deliver the required product? Demand reduction can ease pressure too, but through costs borne by users. None of these mechanisms supplies a reliable war forecast.
Federal Reserve History: 1973–74 oil shock ↗Federal Reserve History: 1978–79 oil shock ↗EIA: 2019 Saudi outage ↗
Lens analysis
A durable easing would need to work through the chain: less disruption or more replacement supply, less pressure in refined-fuel markets, workable shipping and wholesale reductions reaching retailers. Exchange rates and retail competition can reinforce or offset that movement.
For a household, compare local pump prices rather than treating a global oil headline as tomorrow's price board. For judging the wider story, follow sustained deliveries and product benchmarks, not merely a promised reopening. The scenarios below identify what to watch without pretending to attach odds to a war.
ACCC weekly fuel monitoring ↗AIP terminal gate prices ↗EIA World Oil Transit Chokepoints ↗
Scenario: verified safe transit for some cargoes improves usable supply. Watch repeated voyages, published terms and insurer participation. Direction: lower disruption pressure, with limits from product shortages and exclusions. A signed document without traffic is not the same result.
Scenario: intermittent attacks and uncertain permissions keep shipping unreliable. Watch cancellations, transit persistence and replenishment of stocks. Direction: continuing cost pressure and substitution. No fixed pump-price path follows.
Scenario: damage spreads to pumps, processing plants or terminals. Watch verified outages and repair updates, not social-media battle claims. Direction: less deliverable supply and greater risk premiums. Severity depends on redundancy and stocks.
Scenario: repairs, pipeline operations and safe port departures restore flows outside Hormuz. Watch actual delivered volumes and destination routes. Direction: pressure can ease before a full settlement; crude recovery alone does not guarantee diesel or LNG recovery.
The earlier Lens investigation closed its evidence on 18 August. The 18 September edition recorded Saudi bypass damage and higher Australian wholesale prices. Reuters then reported a low-flow pipeline restart on 22 September. That weakens the earlier expectation of a weeks-long complete outage, but does not establish normal exports or lower pump prices.
Oil needs a usable route to a refinery and fuel needs a usable route to a buyer. Reuters reported the Saudi East-West pipeline restarted on 22 September, initially at low flow. Whether that becomes reliable exports and lower Australian fuel costs remains open; refined-fuel markets, currency, tax and retail timing also matter.
AIP's dated wholesale observations and ACCC's separation of international prices, wholesale prices, taxes and retail outcomes.
Oil needs a usable route to a refinery and fuel needs a usable route to a buyer. Reuters reported the Saudi East-West pipeline restarted on 22 September, initially at low flow. Whether that becomes reliable exports and lower Australian fuel costs remains open; refined-fuel markets, currency, tax and retail timing also matter.
Supply substitutions and repaired infrastructure can ease pressure before a comprehensive peace. A market price can fall during continuing conflict.
Follow-up to the 18 August investigation, updated 24 September. Domestic wholesale observations to 17 September; ACCC retail update to 18 September; pipeline restart is attributed Reuters reporting from 22 September. These later developments are separate from the EIA forecast closed 3 September.
AI-assisted research and writing. Evidence checked 2026-09-18.
Brisbane daily indicative wholesale ULP and diesel, GST inclusive, 11–17 September 2026; not pump prices.
A1 · Published date not stated · Checked 2026-09-18Prices to 9 September; full excise restoration on 3 August; refined benchmarks and domestic price transmission.
A1 · Published 2026-09-11 · Checked 2026-09-18Forecast inputs closed 3 September. August Brent average $91/barrel and forecast export constraints. Does not incorporate later attacks.
A2 · Published 2026-09-09 · Checked 2026-09-18Route geography and historical throughput; capacity is not current deliverable output. Data mainly first half 2025.
A2 · Published 2026-03-03 · Checked 2026-09-18Two regional officials say pipeline mostly unavailable for weeks; repair duration is attributed reporting.
B1 · Published 2026-09-14 · Checked 2026-09-18Three sources briefed on the matter reported a pipeline restart at low flow; normal capacity and Yanbu exports were not established.
B1 · Published 2026-09-22 · Checked 2026-09-24Reported expansion of Red Sea conflict and risks to facilities and tankers; not an independent military assessment.
B1 · Published 2026-09-17 · Checked 2026-09-18Kpler-derived weekend transit reporting, attacks and stalled talks. Page dates differ between search cache and opened page; event described as preceding weekend, not execution-day count.
B1 · Published 2026-09-18 · Checked 2026-09-18Oman postpones proposed regional Hormuz meeting; does not establish diplomacy has ended.
B1 · Published 2026-09-13 · Checked 2026-09-18Indexed Reuters report says prices settled lower but above $100/barrel. Full retrieval unavailable; no precise settlement admitted.
B1 · Published 2026-09-17 · Checked 2026-09-18Historical embargo, price increase and inflation context; mechanism comparison, not forecast.
A2 · Published date not stated · Checked 2026-09-18Iranian production loss, demand and precautionary buying contributed to price pressure.
A2 · Published date not stated · Checked 2026-09-18Physical processing outage and immediate market response; does not establish 2026 repair time.
A2 · Published 2019-09-16 · Checked 2026-09-18Establishes the earlier Lens treatment and its cutoff; not independent corroboration of war events.
C · Published 2026-08-18 · Checked 2026-09-18Possible effects · We cannot say how likely
The Saudi bypass has reportedly restarted at low flow, which could ease one constraint if reliable throughput and Yanbu exports recover. Australian pump prices still depend on refined-fuel markets, currency, tax and retail timing; a restart alone does not establish a price fall.
Shipping and export routes were disrupted in mid-September; Reuters then reported the Saudi East-West pipeline restarted at low flow on 22 September. Australian wholesale fuel prices had risen in the earlier measured window.
If the restart becomes sustained delivered supply and shipping risk eases, replacement costs could fall through refined-fuel benchmarks and later Australian wholesale prices. If capacity or safe passage remains constrained, pressure could persist.
Where the connection stopsA reported restart is not verified full output, confirmed Yanbu loadings or an Australian retail-price effect.
How people may respond
How conflict and shipping disruption are interpreted could alter price expectations, purchasing and policy attention before the full Australian transmission chain is visible.
What the evidence does not showThe route and price mechanisms are supported; expectation effects and any precise local attribution are not measured.
Shipping, capacity and price records are presented as a multi-step constraint.
Market and policy actors may expect higher replacement costs to persist.
Attention moves to inventories, alternative supply and wholesale transmission.
Importers, retailers and governments: Change procurement, stock or relief decisions if constraints persist.
Commercial and policy settings may commit to a longer disruption horizon.
What we know has changedWe have not established that this possible change has happened.
What this does not showExpectations do not establish the duration or exact pump-price effect.
This is the first time Lens has mapped this path. We have no later evidence showing whether it is happening more, less or about the same.
Conflict remains salient even as route and wholesale indicators can recover.
Readers may continue to attribute later prices to the war after the specific pressure has eased.
Attention stays on the conflict while tax, currency and retail cycles regain importance.
Media, consumers and policymakers: Reassess the attribution as route and price series diverge.
The war-related component can weaken without every retail price falling immediately.
What we know has changedWe have not established that this possible change has happened.
What this does not showRecovery in one link does not remove all fuel-price pressures.
This is the first time Lens has mapped this path. We have no later evidence showing whether it is happening more, less or about the same.
If the restarted pipeline remains at low or irregular flow, Yanbu loading stays constrained, or wider shipping risk limits delivered supply
Then Australian wholesale and retail fuel could remain exposed to higher replacement costs and volatility after normal transmission delays.
Would weaken this: Transit and alternative capacity recover quickly. Australian wholesale prices fall despite the reported constraints.
Scope: Australian fuel-price exposure, not a prediction for one retailer or household. Horizon: Successive weekly price and route updates.
If the reported pipeline restart becomes sustained usable throughput and port loadings recover alongside safer transit or alternative supply
Then the conflict premium could fade even while Australian prices continue to reflect tax, currency, inventories and retail cycles.
Would weaken this: Fresh attacks or outages remove capacity again. Refined-fuel shortages persist after crude-route conditions improve.
Scope: The route-related component of fuel pressure. Horizon: Near-term market and infrastructure updates.
Brisbane daily indicative wholesale ULP and diesel, GST inclusive, 11–17 September 2026; not pump prices.
Open evidence ↗Prices to 9 September; full excise restoration on 3 August; refined benchmarks and domestic price transmission.
Open evidence ↗Forecast inputs closed 3 September. August Brent average $91/barrel and forecast export constraints. Does not incorporate later attacks.
Open evidence ↗Route geography and historical throughput; capacity is not current deliverable output. Data mainly first half 2025.
Open evidence ↗Kpler-derived weekend transit reporting, attacks and stalled talks. Page dates differ between search cache and opened page; event described as preceding weekend, not execution-day count.
Open evidence ↗Three sources briefed on the matter reported a pipeline restart at low flow; Yanbu export resumption was still prospective. This does not verify sustained full capacity.
Open evidence ↗What could change this assessment?
What changed since we last looked
Still true: The mechanism still depends on reliable delivered supply, refined-fuel benchmarks and later Australian wholesale transmission.
We still cannot conclude: The restart report does not establish normal capacity, sustained Yanbu exports, a ceasefire or lower Australian pump prices.
Read the earlier Iran-war investigation →
Keep this in Focus
Follow the existing Iran-war Focus for material changes to the answer.
Material changes only. Email updates can be stopped at any time.
Free Lens updates
Our free weekly email brings you the latest Lens reporting and what changed.